Here’s a hypothetical to start with. You quote a $9,000 HVAC system replacement with no required deposit, and the homeowner is ready to sign on one condition: “Can I do 0% for 24 months?”
If they finance the full $9,000 through Wisetack on an interest-bearing plan or the standard 3-month 0% option, your fee is 3.9%, or $351. If you’ve enrolled in Wisetack’s longest 0% APR add-on and they take the 24-month 0% term, the fee on the same job is 9.9%, or $891. That’s $540 more for the same equipment, the same crew and the same install day.
Wisetack’s default fee is 3.9% of the financed amount, with no setup fee, subscription or card-processing fee on top. It goes up only if you enroll in an extended 0% APR add-on and a customer who qualifies picks one of those longer 0% terms: 4.9% for 6 months, 9.9% for 24 months. Either way, you’re paid after the customer confirms the job is done, not when they sign.
Everything below comes from Wisetack’s own onboarding and comparison pages and from the Jobber and Housecall Pro help centers, checked October 17, 2026. These are published US merchant fees in US dollars, not figures from a Wisetack account or a real payout statement, and every job in this post is an illustration.
Who decides whether a job costs you 3.9% or 9.9%?
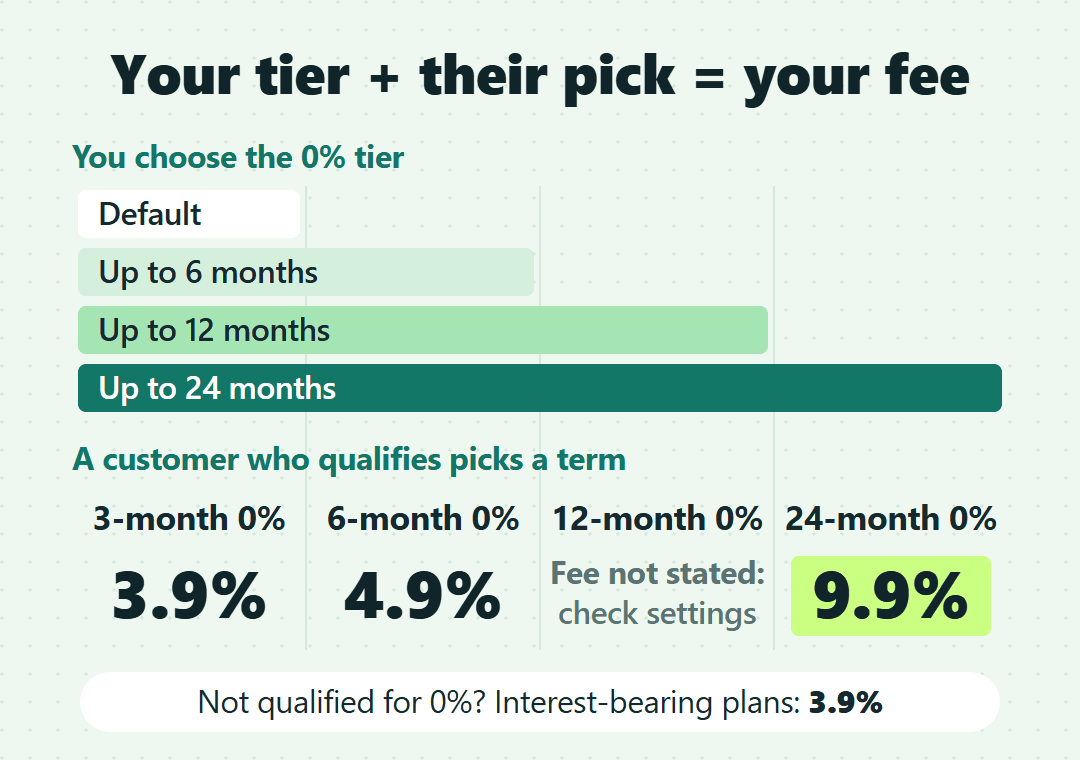
You decide which 0% terms are on the menu. Your customer decides which one gets used, and that choice sets your fee on that job.
A 3-month 0% APR option comes with Wisetack at the standard 3.9%. On top of that, you can enroll in an add-on tier: Up to 6 months, Up to 12 months or Up to 24 months at 0% APR. Enrolling doesn’t cost anything by itself; it adds longer 0% choices to what a qualified customer sees.
| What the customer picks | Your merchant fee | When that choice appears |
|---|---|---|
| An interest-bearing plan | 3.9% | Customer is approved for financing |
| 3-month 0% APR | 3.9% | Included by default; customer qualifies for 0% |
| 6-month 0% APR | 4.9% | You enrolled in Up to 6 months or longer; customer qualifies for 0% |
| 24-month 0% APR | 9.9% | You enrolled in Up to 24 months; customer qualifies for 0% |
The 4.9% and 9.9% figures are the examples in Housecall Pro’s help center, and Wisetack’s own comparison page describes its fee as “up to 9.9% for 24-month 0% APR.” Fees as published in October 2026.
The 12-month 0% term is part of the Up to 12 and Up to 24 tiers, but none of the Wisetack, Jobber or Housecall Pro pages behind this post state its fee. Don’t estimate it from the 6- and 24-month numbers; look for it in your financing settings when you choose a tier, or ask Wisetack.
Two things keep the higher fees narrower than they look. Only customers who are well qualified for 0% see the extended 0% terms; everyone else who’s approved sees interest-bearing options, which cost you 3.9% whatever rate the customer gets. And you can unenroll anytime and go back to 3-month 0% at 3.9%.
On the $9,000 example from the top, here’s how the three published fees line up. The 6-month 0% term lands in between at $441.
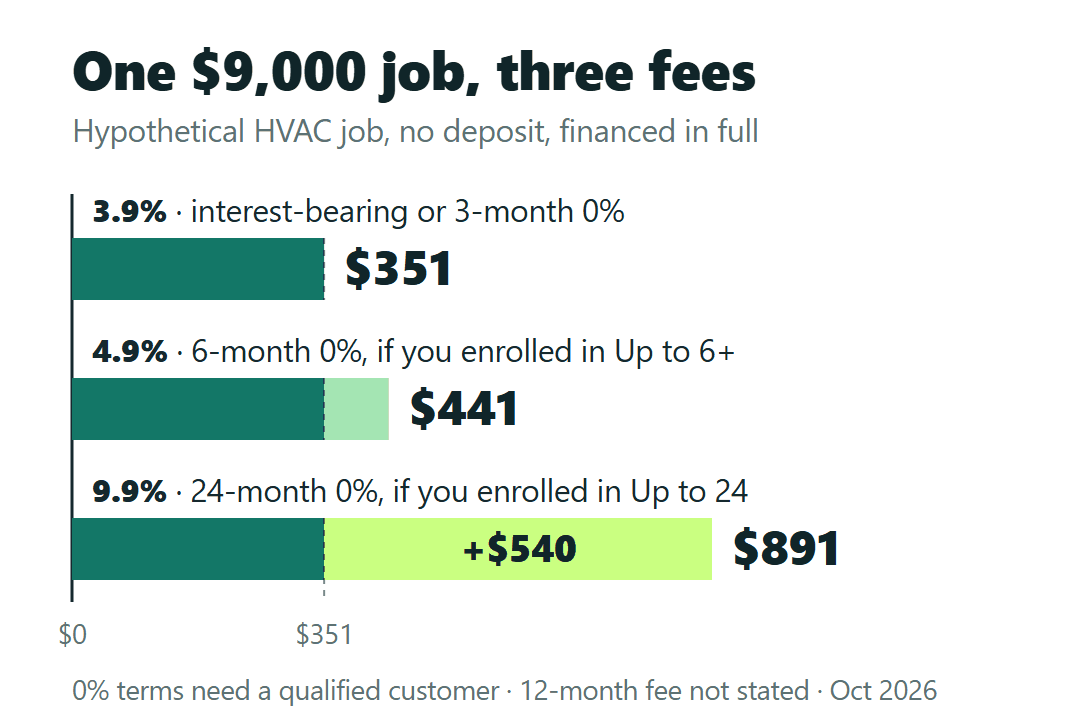
My practical reading: enrolling in Up to 24 months isn’t a price increase on every financed job. It lets some qualified customers move some jobs from 3.9% to 9.9%, and you won’t know which jobs until they choose.
One caveat about the menu itself. Housecall Pro’s help center documents the add-on tiers, while Jobber’s Wisetack article lists only a fixed 3.9%, and Wisetack notes that not every merchant takes part in 0% programs. Whatever software you quote from, open its financing settings and confirm which 0% options you can actually offer.
The fee is charged on the financed amount, not always the quote
Wisetack takes its fee out of the financed amount before the money reaches you. If you don’t require a deposit and the customer is approved for the whole job, the financed amount is simply the quote total.
Financed amount = quote total − required deposit
Fee = financed amount × the rate for the customer’s choice (3.9%, 4.9% or 9.9%)
Payout = financed amount − fee
Wisetack can’t finance a deposit. When your quote has a required deposit, the customer pays that part up front out of pocket and financing covers the rest. A 100% deposit means financing isn’t offered at all.
Example: a $14,000 roof with a 25% deposit
Take a hypothetical $14,000 roof replacement with a 25% required deposit. The customer pays $3,500 up front, and $10,500 goes through Wisetack.
| Same $14,000 job | Financed through Wisetack | Fee at 3.9% | Fee at 9.9% (24-month 0%) |
|---|---|---|---|
| No required deposit | $14,000 | $546.00 | $1,386.00 |
| 25% required deposit ($3,500) | $10,500 | $409.50 | $1,039.50 |
The 9.9% column applies only if you enrolled in Up to 24 months and the customer qualifies and takes that term. In the 3.9% case with the deposit, Wisetack pays out $10,090.50, on top of the $3,500 you already collected.
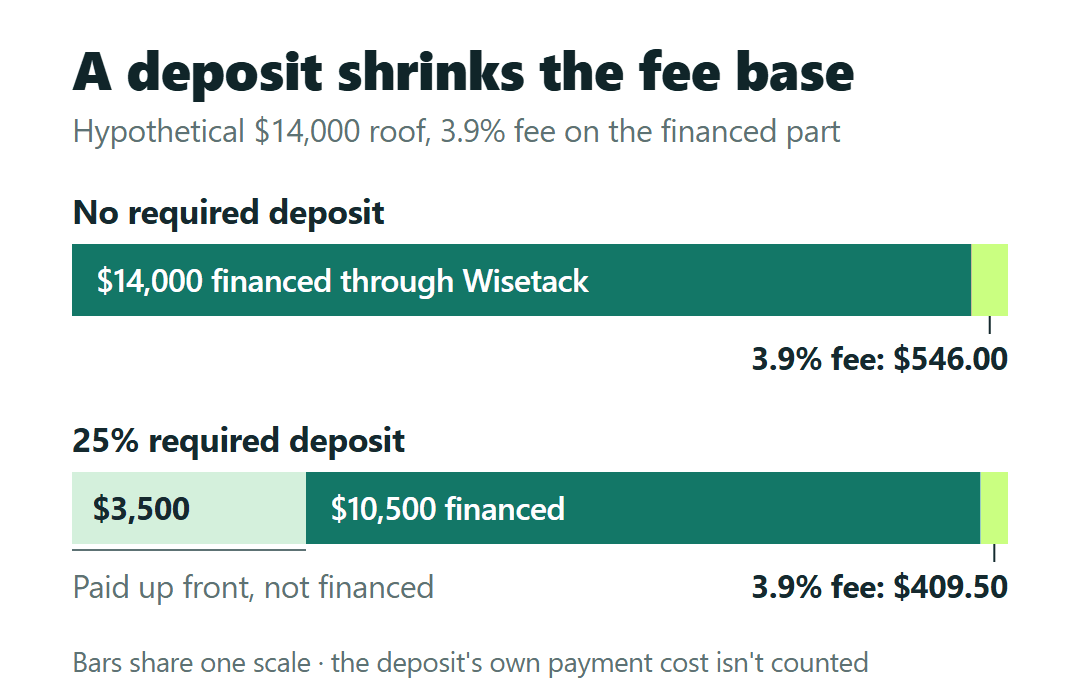
The deposit itself is paid however you normally take payments, and that method’s cost isn’t counted here.
When the price moves after approval
The approved amount doesn’t follow the job. If the final invoice comes in higher, the customer pays the difference another way. If the price drops, edit and resend the quote so the customer can re-apply; the original application expires, and expired applications carry no fee.
If Wisetack approves the customer for less than the full job, the rest is paid another way too. Your fee is figured on what’s financed, not on the job total.
You get paid when the customer says the job is done
Signing the loan doesn’t release your money. Wisetack pays out only after the customer selects “Job is done – release payment” in their application. It sends the funds the next business day, and they take 1–3 business days to arrive depending on your bank.
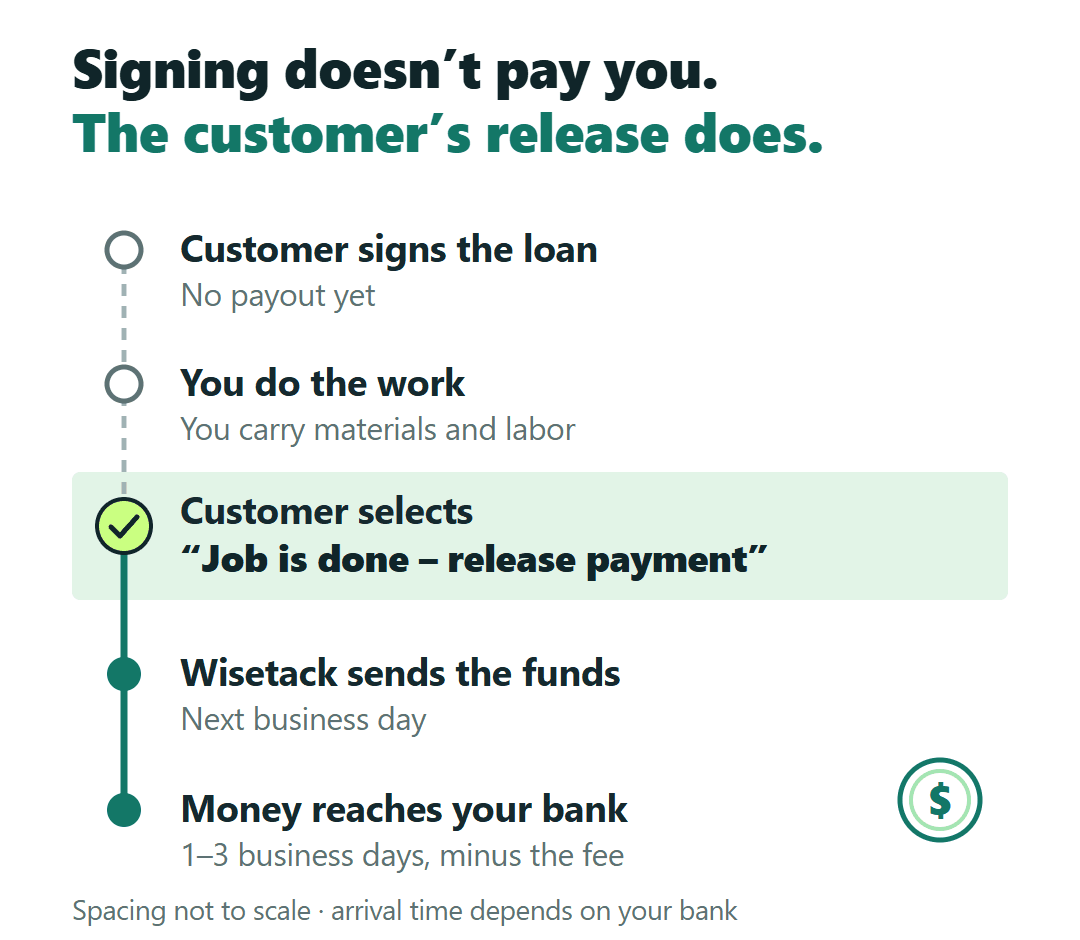
On a one-day repair that barely registers. On a roof or a full system replacement, you’re carrying materials and labor until that confirmation comes in, so tell the homeowner at signing that the release step is theirs.
A required deposit is the one part of a financed job you collect before the work starts, and it shrinks the base the fee is charged on. The trade-off is that the homeowner pays it out of pocket, which some may not want.
Will your business and this job qualify?
Financing is offered on jobs from $500 up to $65,000. That top figure is a ceiling, not everyone’s limit: Wisetack sets each business’s maximum, and Jobber notes that it’s common to start below $65,000.
If you sign up through Jobber
Jobber’s help center lists its own conditions for the Wisetack integration:
- Any Jobber plan except Lite
- A US business doing one-off work, not a repeating schedule
- Not in pool and spa, residential or commercial cleaning, window washing or snow removal
- 10 or more online reviews averaging about 4.5 stars
- Over $12,500 in monthly revenue or $150,000 a year
Processing the application can take up to five business days. Those conditions belong to the Jobber route; Wisetack’s own site lists a federal EIN, owner details and business bank verification for sign-up, with no personal credit check.
Stay at 3-month 0%, or offer the longer terms?
Staying at the default costs nothing extra. You get the 3-month 0% option and every interest-bearing plan at 3.9%, and the fee on any job is the financed amount × 0.039.
Enrolling in a longer tier is a different call. On the $9,000 example it’s $351 versus $891 whenever a qualified homeowner takes 24 months, and whether that trade pays off depends on how often long 0% terms close jobs for you, which no published page can answer.
If you want to try it without the widest gap, Up to 6 months keeps the highest published 0% fee at 4.9%. You can unenroll anytime.
Before you quote the next large job, open your financing settings and look at two things: which 0% tier you’re enrolled in, with the fee each term carries, and the maximum Wisetack has set for your business. If you’re coming in through Jobber, run down its eligibility list first.
If any of that isn’t spelled out in your account, these are worth putting to Wisetack support:
What merchant fee applies to each 0% term in my current tier, including 12 months? What is my current financing limit, and can it be reviewed? If a financed job is refunded or canceled, what happens to the fee?
Then quote the job knowing what the homeowner’s choice can turn your 3.9% into.
Sources: Wisetack: Getting started with Jobber · Wisetack vs. Service Finance (Wisetack) · Jobber Help: Jobber and Wisetack Consumer Financing Integration · Housecall Pro Help: 0% APR Add-ons with Wisetack